
A consumer Chapter 7 is short — a straightforward case runs about three to four months from filing to discharge — and almost all of the work happens before anything is filed. What usually decides how the case goes is eligibility, exemptions and the accuracy of the schedules. The parts people fear, the hearing and the trustee, are usually the least eventful.
This is a description of the procedure, not legal advice. Nothing here is a recommendation about whether to file.
Before filing: two things that must already be true
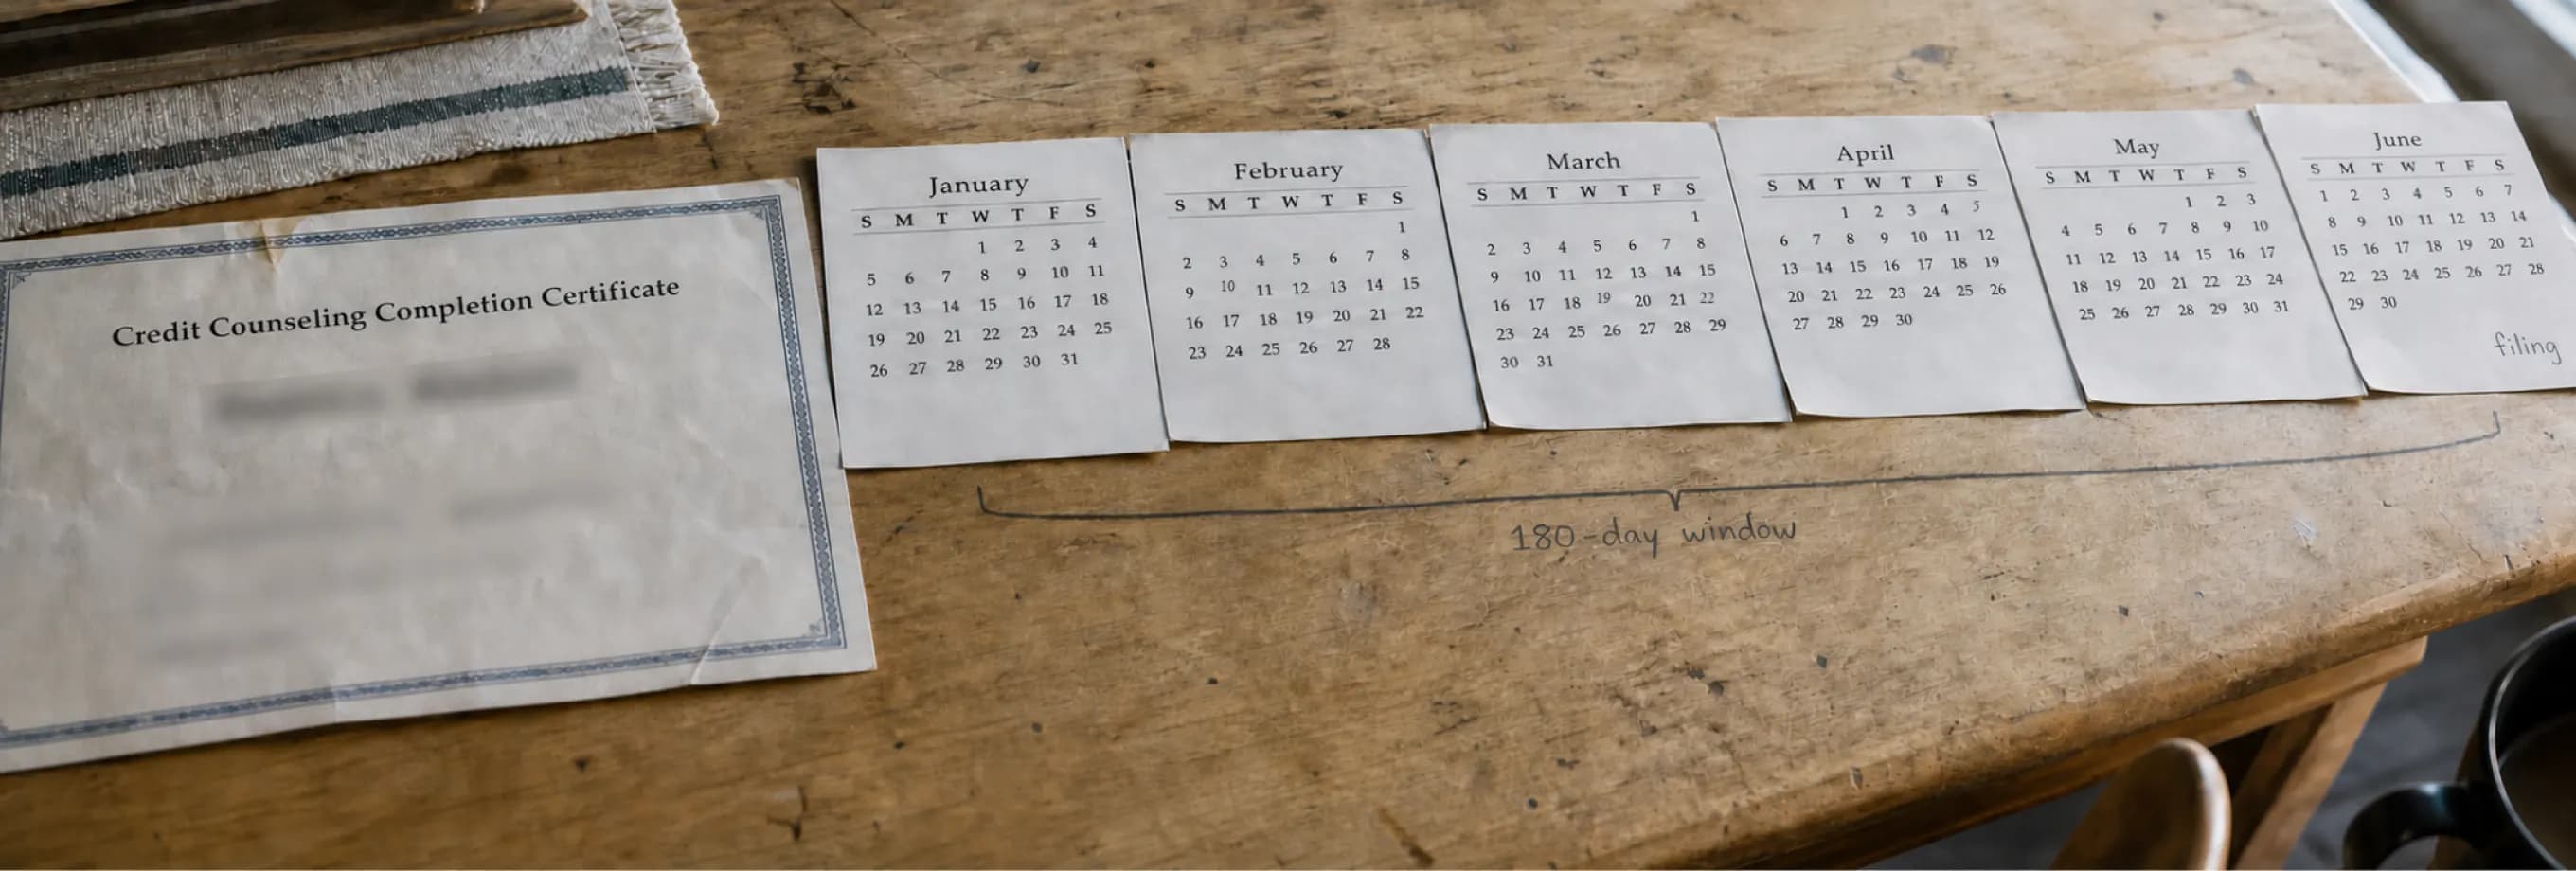
Credit counseling. With narrow exceptions, an individual must complete a briefing from an approved credit counseling agency within the 180 days before filing. The U.S. Trustee Program publishes the approved list. Filing without it, and without qualifying for one of the narrow exceptions, is a genuinely common way for self-filed cases to be dismissed on day one.
Eligibility under the means test. The calculation has its own page — the Chapter 7 means test after a job loss — and in outline it is this. Compare household income against the California median published by the U.S. Trustee Program, and if you are above it, compute disposable income after allowed expenses. Being over the median does not disqualify you; that is the second half of the test, and many over-median filers pass it.
Step 1 — File the petition and schedules
Core forms: Form 101 (voluntary petition), the Schedules — A/B (property), C (exemptions), D (secured creditors), E/F (priority and unsecured creditors), G (contracts and leases), H (codebtors), I (income), J (expenses) — Form 106Dec (declaration), Form 107 (statement of financial affairs), Form 121 (statement about your Social Security number), and Form 122A-1 with 122A-2 if applicable. Form 108 (statement of intention) is added where there are secured debts or leases of personal property, and a given case may call for more.
Fee: $338, made up of a $245 filing fee, a $78 administrative fee and a $15 trustee surcharge. It can be paid in installments; a waiver is available where household income is below 150 percent of the applicable poverty guideline and the filer cannot pay in installments.
Where you file: California has four federal judicial districts — Central (Los Angeles, Orange, Riverside, San Bernardino, Ventura, Santa Barbara, San Luis Obispo), Eastern (Sacramento, Fresno and the inland counties), Northern (San Francisco, Oakland, San Jose, Santa Rosa) and Southern (San Diego, Imperial). Each has divisional offices and its own local rules.
Where it goes wrong: the schedules are signed under penalty of perjury and must be complete — every asset, every creditor, every transfer in the lookback periods. An omission is not a paperwork problem; it is the thing that turns a routine case into a contested one.
Step 2 — The automatic stay begins
Filing triggers the stay under 11 U.S.C. § 362. Collection stops: calls, lawsuits, wage garnishment, foreclosure sales, repossession — immediately and without any further order. A creditor can ask the court to lift it, and for someone who has filed before within a year the stay may last only 30 days or not arise at all.
The stay has exceptions. Most relevant to families, § 362(b)(2) leaves running the establishment and modification of support orders, custody and visitation proceedings, paternity actions, domestic violence proceedings, and the collection of support from property that is not property of the estate. Bankruptcy does not stop child support.
Step 3 — The trustee, and what "no-asset" means
The court appoints a Chapter 7 trustee whose job is to identify property that is not exempt and turn it into money for creditors.
Most consumer cases turn out to be no-asset cases. The trustee reviews the schedules, concludes there is nothing left to distribute after exemptions, and files a report of no distribution. Creditors are then told not to file proofs of claim unless the court later says otherwise.
Whether your case is a no-asset case is decided by exemptions, and California requires electing one of two systems for the entire case, compared line by line here: the 704 system with its large homestead, or the 703 system, whose residence exemption is small but whose wildcard can be applied to anything — $1,950 plus whatever part of the $36,750 residence exemption goes unused, so up to $38,700. Those figures come from Judicial Council form EJ-156 and govern cases commenced from April 1, 2025 through March 31, 2028.
As shorthand, 704 is the system for substantial home equity and 703 the flexible one when assets are spread across categories — but it is only shorthand, because 703 has its own limit for each category.
Step 4 — The 341 meeting
About a month after filing, the meeting of creditors under 11 U.S.C. § 341. It is conducted by the trustee, not a judge, and in California districts it is commonly held remotely — though the format is set by the district and by the notice in your own case.
You are placed under oath and asked to confirm identity and that the schedules are accurate and complete, plus questions specific to your case. It typically takes a few minutes. Creditors may attend; in ordinary consumer cases they almost never do.
Bring government photo identification and proof of your Social Security number. Missing either is a common reason a meeting is continued.
Step 5 — Debtor education
After filing and before discharge, complete a personal financial management course from an approved provider and file Form 423.
Where it goes wrong: a case can be closed without a discharge because this certificate was never filed. Reopening to fix it costs a fee. It is a twenty-dollar course that people forget because it comes after the part that felt important.
Step 6 — Discharge
The discharge typically arrives around 60 to 90 days after the 341 meeting — the window for objections. It wipes out personal liability for dischargeable debts.
It does not touch:
- domestic support obligations, and property division obligations owed to a former spouse;
- most taxes;
- most student loans, unless undue hardship is established in a separate adversary proceeding;
- debts for death or personal injury caused by driving under the influence;
- criminal fines and restitution;
- debts obtained by fraud, where a creditor objects and succeeds;
- liens. A discharge ends personal liability, not a mortgage or car lien. Keep the collateral, keep paying — or surrender it.
The timeline
| Step | When |
|---|---|
| Credit counseling | Within 180 days before filing |
| Petition and schedules filed; stay begins | Day 0 |
| Trustee appointed | Days after filing |
| 341 meeting | About 1 month after filing |
| Debtor education certificate (Form 423) | After filing, before discharge |
| Discharge | Roughly 60–90 days after the 341 meeting |
What decides the outcome
Not the hearing. Three things, all settled before filing:
- Eligibility — the means test, and whether Chapter 13 is the better instrument.
- Exemptions — 703 or 704, and whether everything you own is actually covered.
- Accuracy — schedules that are complete, and transfers in the lookback periods disclosed rather than discovered.
Errors in all three are found after they can be undone. Bankruptcy filing fees are low and the courts publish the forms free, but this is the area where the gap between a competently prepared case and a self-prepared one is widest. Many California bankruptcy attorneys offer a free initial consultation.
This directory lists licensed California bankruptcy attorneys by county with their State Bar record. You contact them directly — we are a directory, not a referral service, and nothing here is legal advice.
Of the 5,012 active California attorneys listed in this directory, 1,523 list bankruptcy among their practice areas. Only 66 are certified specialists in Bankruptcy Law under the State Bar's Board of Legal Specialization. That credential is a separate thing from practicing bankruptcy, so the smaller number is not a count of the attorneys competent to handle a case.
Common questions
- What are the steps of a Chapter 7 bankruptcy?
- Complete a credit counseling course; file the petition, schedules and means test forms; the automatic stay begins; a trustee is appointed; attend the meeting of creditors about a month later; complete a debtor education course; receive the discharge, typically around 60 to 90 days after the meeting.
- How much does it cost to file Chapter 7?
- The court charges $338 — a $245 filing fee, a $78 administrative fee and a $15 trustee surcharge. It can be paid in installments, and a waiver is available where household income is below 150 percent of the applicable poverty guideline and the filer cannot pay in installments.
- What is the 341 meeting?
- The meeting of creditors required by 11 U.S.C. § 341, conducted by the trustee rather than a judge, usually about a month after filing. The filer is placed under oath and asked about the schedules. Creditors may attend and usually do not.
- What debts are not discharged in Chapter 7?
- Among others, domestic support obligations, most taxes, most student loans absent an undue hardship determination, debts for death or injury from driving under the influence, criminal fines and restitution, and property division obligations owed to a former spouse.
- Will I lose my property?
- Most consumer Chapter 7 cases are no-asset cases in which the trustee realizes nothing. What you keep is decided by exemptions, and California requires choosing between two exemption systems for the whole case.
- Which bankruptcy court do I file in?
- California has four federal judicial districts — Central, Eastern, Northern and Southern — each with its own bankruptcy court and divisional offices. Venue depends on where you have lived for the greater part of the past 180 days.
Sources
Checked on August 16, 2026. Where this page and a court’s own published material disagree, the court is authoritative.
- United States Courts — Chapter 7 bankruptcy basics (opens in a new tab)
- United States Courts — bankruptcy forms (opens in a new tab)
- 11 U.S.C. § 362 — the automatic stay (opens in a new tab)
- 11 U.S.C. § 341 — meeting of creditors (opens in a new tab)
- 11 U.S.C. § 523 — exceptions to discharge (opens in a new tab)
- U.S. Trustee Program — approved credit counseling and debtor education providers (opens in a new tab)
- United States Courts — bankruptcy court miscellaneous fee schedule (opens in a new tab)
- California Courts form EJ-156 — exemption amounts effective April 1, 2025 through March 31, 2028 (opens in a new tab)